Home health and home care sound like they ought to be the same thing. They’re one word apart, they both happen at home, and whoever named them clearly never had to explain the difference at a hospital discharge. But they describe two very different kinds of help, paid for in very different ways, and mixing them up is one of the most common surprises families run into after a parent’s hospital stay.
This guide covers what each type of care is, who provides it, how it’s typically paid for, and why many families end up using both at the same time.
When the Help Isn’t What the Family Expected
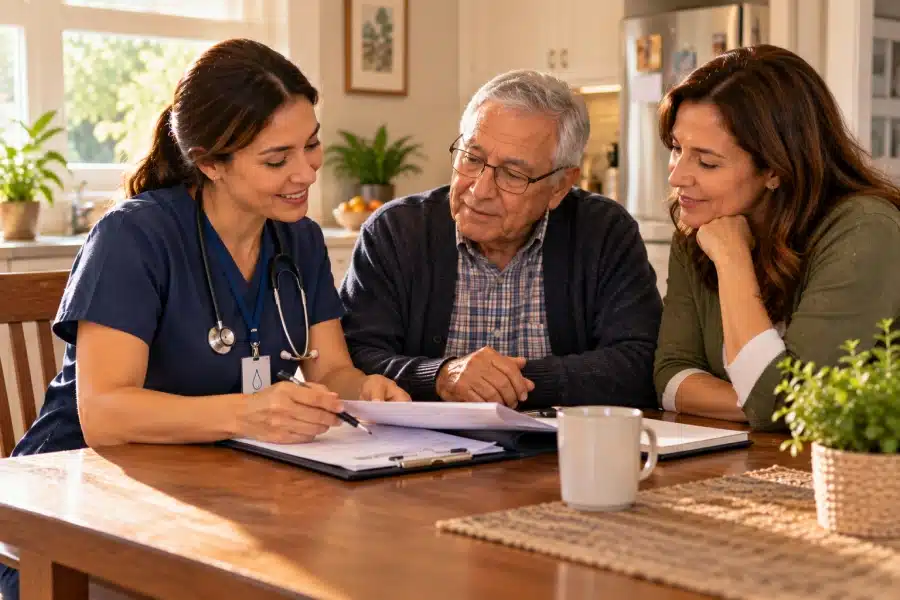
Picture a family bringing Dad home after a hospital stay for pneumonia. Before discharge, the hospital’s case manager mentions that home health has been arranged, and everyone breathes a sigh of relief. Then the first week unfolds. A nurse comes by twice to check his breathing and go over his medications. A physical therapist visits to work on his strength and walking. Each visit lasts under an hour.
Between visits, no one is there to help him shower, fix lunch, or steady him on the way to the bathroom at night. His daughter, who lives 40 minutes away, starts to realize that the help she pictured and the help that was arranged are two different things. That gap is the difference between home health and home care, and it’s much easier to plan around once you know it’s there.
The Short Version
- Home health care is medical care at home. It’s ordered by a doctor, provided by licensed clinicians such as nurses and therapists, usually short-term, and often covered by Medicare when eligibility rules are met.
- Home care is non-medical help with daily life. It covers things like bathing, meals, housekeeping, errands, and companionship, can continue for months or years, and is mostly paid for privately.
- Many families use both. Home health handles the medical side of recovery, and home care fills in the hours and tasks home health doesn’t cover.
What Home Health Care Is
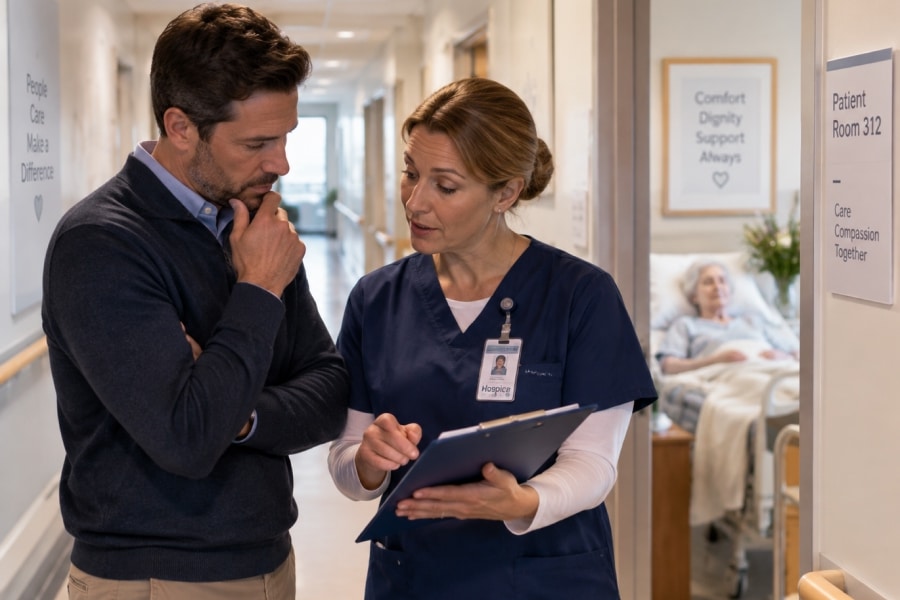
Home health care brings skilled medical services into the home, typically to help someone recover from an illness, injury, surgery, or hospital stay, or to manage a health condition that has recently changed. According to Medicare’s home health coverage page, covered services include:
- Part-time or intermittent skilled nursing care
- Physical therapy, occupational therapy, and speech-language therapy
- Medical social services
- Home health aide help with personal care, but only alongside skilled nursing or therapy
- Durable medical equipment and medical supplies for use at home
Visits follow a plan of care, and the goal is usually to help the person regain as much independence as possible or stabilize a condition, not to provide ongoing daily help. Our guide to home health care for seniors covers these services in more detail.
Who Qualifies Under Medicare
Medicare generally covers home health care when all of the following apply:
- A doctor or other allowed health care provider has ordered the care and set up a plan of care.
- The person needs part-time or intermittent skilled care, not round-the-clock care.
- The person is considered homebound, which generally means leaving home isn’t recommended because of their condition, or takes a lot of effort and help. This is less strict than it sounds, and our article on what homebound means for home health eligibility explains how it works in practice.
- The care comes from a Medicare-certified home health agency.
What Home Health Costs
- For people with Original Medicare who qualify, there’s generally no cost for covered home health services themselves.
- Medical equipment is handled differently. After the Part B deductible, the person typically pays 20% of the Medicare-approved amount.
- Skilled nursing and home health aide time combined is generally limited to 8 hours a day and 28 hours a week, though a provider may approve somewhat more for a short period (up to 35 hours a week).
- Medicare Advantage plans (private plans that provide Medicare benefits) cover home health too, but they often use provider networks and may require prior authorization, meaning approval from the plan before services begin. Our article on Medicare Advantage and home health care walks through those differences.
- Medicaid also covers home health. It’s listed among the mandatory Medicaid benefits that state programs are expected to provide, though eligibility rules and program details vary by state.
What Home Care Is
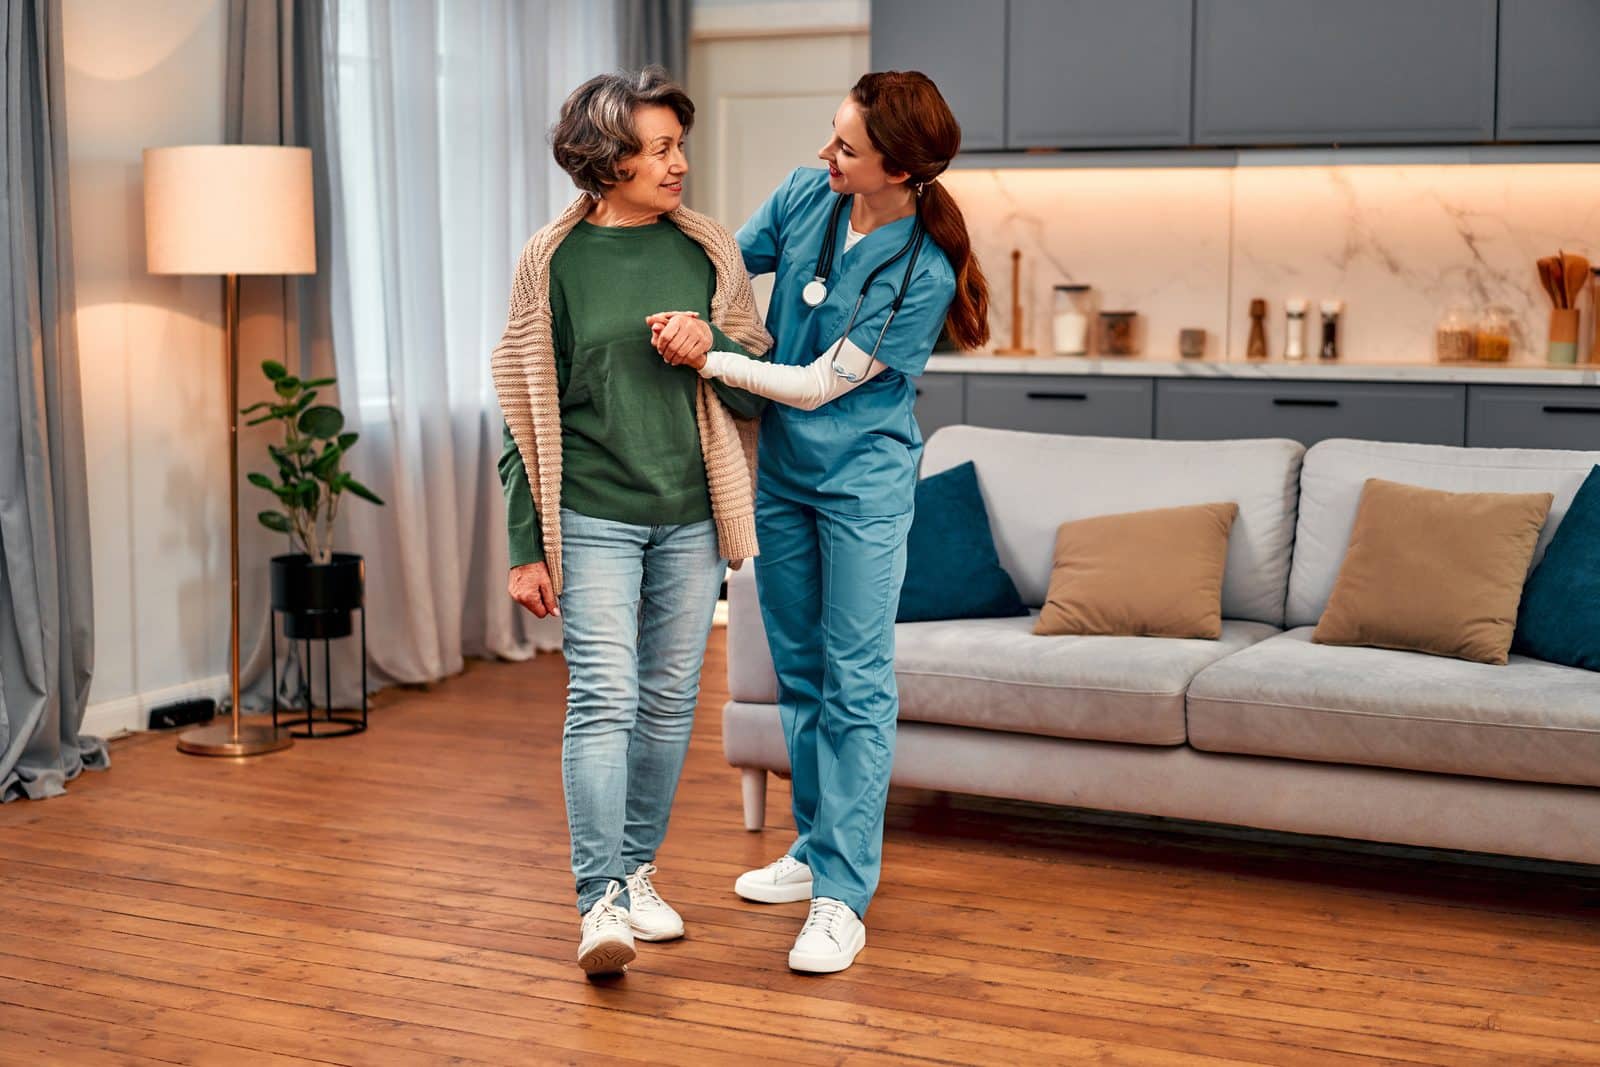
Home care, sometimes called in-home care, non-medical home care, or custodial care, is help with the everyday tasks that get harder with age, illness, or memory loss. It’s provided by caregivers, personal care aides, and companions rather than nurses or therapists, and it typically includes:
- Personal care, such as bathing, dressing, grooming, and help using the bathroom
- Help getting in and out of bed or a chair and moving safely around the house
- Meal preparation and help with eating
- Light housekeeping and laundry
- Medication reminders (as opposed to giving medications)
- Transportation to appointments and errands
- Companionship and supervision, which can matter a great deal for someone who lives alone or is living with dementia
Home care can be as little as a few hours a week or as much as around-the-clock help, and it can continue for as long as the family needs it. There’s no doctor’s order or homebound requirement. Families usually arrange it directly with a home care agency or an independent caregiver.
For a closer look at the two main types, see our guides to personal care assistance for seniors and companion care for seniors, or our side-by-side look at personal care vs. companion care.
How Families Typically Pay for Home Care
This is where the two kinds of care differ the most. According to Medicare’s long-term care coverage page, Medicare doesn’t cover custodial care, such as help with dressing, bathing, and using the bathroom, unless medical care is also needed. Families commonly cover home care through:
- Private pay from personal savings, income, or contributions from family members
- Long-term care insurance, depending on the policy’s terms
- Medicaid, which lists personal care as an optional benefit and often covers home care through home and community-based services (HCBS) waivers, with rules and waiting lists that vary by state
- Veterans benefits for eligible veterans and surviving spouses
- Local programs coordinated by Area Agencies on Aging, which may offer limited help with things like meals, homemaker services, or respite
Our guide on how to pay for in-home care goes through each option in more detail. Because Medicaid rules vary by state, families may want to talk with a licensed elder law attorney or Certified Medicaid Planner about their specific situation.
Home Health vs. Home Care at a Glance
- Type of help: Home health is skilled medical care. Home care is non-medical help with daily living.
- How it starts: Home health starts with a doctor’s order and a plan of care. Home care is arranged directly by the family, with no order needed.
- Who provides it: Home health comes from registered nurses, licensed practical nurses, therapists, and supervised home health aides. Home care comes from caregivers, personal care aides, and companions.
- How long it lasts: Home health is usually short-term and tied to a recovery or a change in health. Home care can continue for as long as it’s needed.
- How often: Home health typically means brief, scheduled visits. Home care can range from a few hours a week to 24-hour care.
- Who usually pays: Home health is often covered by Medicare, Medicare Advantage, or Medicaid for those who qualify. Home care is mostly private pay, with some help possible from long-term care insurance, Medicaid programs, or veterans benefits.
- How to compare providers: Medicare-certified home health agencies can be compared on Medicare’s Care Compare tool. Non-medical home care agencies aren’t listed there, so families often rely on interviews, references, and state licensing information where it’s available.
Why Many Families Use Both
Home health and home care aren’t competing choices. They often work side by side, especially after a hospital or rehab stay:
- Home health visits handle the medical side, like a nurse checking a healing incision or a therapist working on balance and walking.
- Home care covers the hours in between, such as help with a morning shower, lunch, a ride to a follow-up appointment, or someone nearby overnight.
- When home health ends because recovery goals have been met, home care can continue, giving families time to see what level of ongoing help makes sense.
- Some agencies offer both home health and home care, while others provide only one. Families often find it helpful to ask exactly which services an agency is licensed to provide.
Back to the family from earlier: once they understood the difference, they kept the home health visits for Dad’s breathing and therapy and added a home care aide for a few hours each morning. The nurse and therapist handled the medical side, the aide handled the rest, and his daughter could stop making the drive every day. Our guide to post-hospital in-home care walks through that transition in more detail.
Common Questions Families Ask
Is a home health aide the same as a home care aide?
Not quite. The daily tasks can look similar, since both may help with bathing and dressing. The difference is the setting around the work:
- A home health aide works under a home health agency’s plan of care, supervised by a nurse or therapist. Under Medicare, aide services are covered only while the person is also getting skilled care.
- A home care aide or personal care aide works for a home care agency or directly for the family. Training requirements, supervision, and payment vary by state and by agency.
Does Medicare pay for home care for someone with dementia?
Generally not, when help with daily activities and supervision is the only care needed. If the person also has a skilled need and meets the home health rules, Medicare may cover home health for that need, including some aide help during that period. Dementia care needs vary a great deal from person to person, so the person’s physician is the best starting point. Our guide to dementia care at home covers the broader picture.
Can someone get home health and home care at the same time?
Yes, and it’s common. When both are in place, families often find it helpful to share the home health plan of care with the home care team, so caregivers know about things like exercises the therapist assigned or symptoms the nurse is watching for.
How do we figure out which one a parent needs?
- For medical needs, a parent’s doctor or the hospital discharge planner is the usual starting point. If the doctor believes skilled care is medically necessary, they can order home health.
- For help with daily living, an Area Agency on Aging can point families to local options. Our guide to what an Area Agency on Aging does explains how they work, and the Eldercare Locator (1-800-677-1116) can connect families with their local agency.
- The National Institute on Aging’s overview of services for older adults living at home is a helpful checklist for thinking through which kinds of help a parent may need.
- For questions about Medicare coverage, a State Health Insurance Assistance Program (SHIP) counselor offers free, unbiased help through SHIP.
Finding the Right Help at Home
The difference between home health and home care comes down to medical versus non-medical, and short-term versus ongoing. Knowing which is which makes it easier to ask the right questions at discharge, understand what Medicare is and isn’t paying for, and plan for the hours in between visits.
Senioridy’s directory lists both kinds of providers. Families can browse home health providers for skilled, doctor-ordered care, or in-home care providers for help with daily life. Many families end up looking at both.
This article is for informational purposes only and does not constitute legal, financial, or medical advice. Medicare coverage rules, Medicaid program details, and cost-sharing amounts are subject to change, and Medicaid benefits vary by state. Medicare Advantage plans may have different network, prior authorization, and cost-sharing rules than Original Medicare. For free, personalized Medicare guidance, contact your State Health Insurance Assistance Program (SHIP) counselor at shiphelp.org, available in every state at no cost. For questions about a specific health condition or care needs, talk with a physician, and for Medicaid planning, consider consulting a licensed elder law attorney. Always confirm current requirements with official program representatives.